 Parth Shah
on
Parth Shah
Register Valuer | CA | CPA | 15+ Years of Experiance
Parth Shah is the Founder and Team Leader of the company, bringing extensive expertise in business valuation and financial advisory.
Introduction
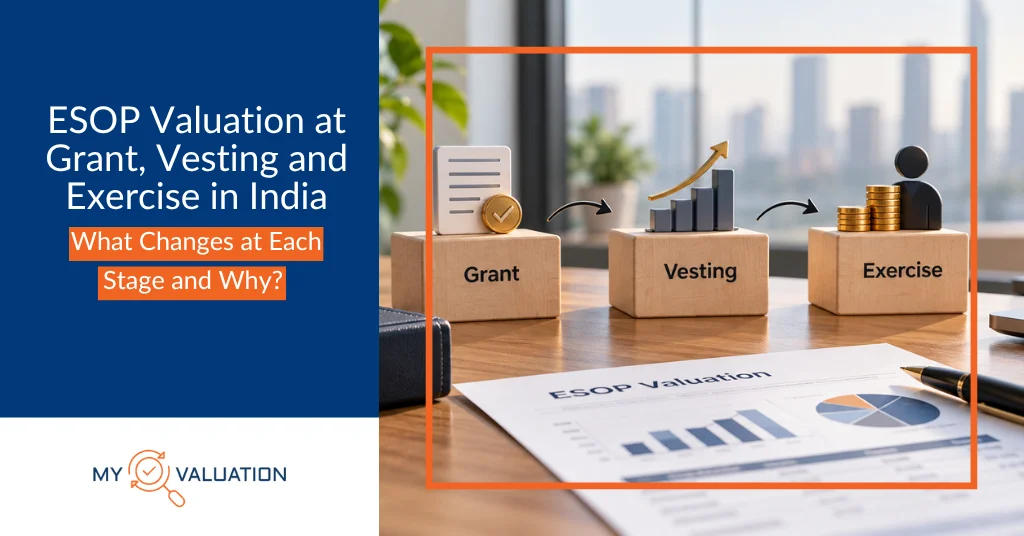
An ESOP has three dates that matter, and only two of them need a valuation. That single sentence clears up most of the confusion founders bring to us.
At the grant date you value the option, for your accounts. At the exercise date you value the share, for employee tax. At vesting, for a standard employee stock option, you value nothing. No report is required, no tax is triggered, and no form is filed.
The two reports are not interchangeable. An ESOP grant date valuation in India is an option fair value under Ind AS 102. An exercise date valuation is a share fair market value under the Income-tax Rules. Using one where the other belongs is the most common ESOP compliance failure we see at MyValuation, and we issue both.
This guide walks the lifecycle stage by stage. For each stage: what is valued, on what date, who signs it, and what does not happen.
Key Takeaways
- An ESOP grant date valuation in India measures the fair value of the option under Ind AS 102, and that number is fixed at grant and never remeasured for equity-settled awards.
- The exercise date valuation measures the fair market value of the share, not the option, and drives the employee’s taxable perquisite.
- Vesting is not a valuation event or a tax event for a standard equity-settled option. It only changes how many options the company expects to vest.
- For unlisted shares, the exercise date FMV must come from a Category I merchant banker registered with SEBI under Rule 15 of the Income-tax Rules, 2026.
- The specified date for that certificate is the exercise date, or an earlier date falling no more than 180 days before it.
- Rule 12(6)(a) of the Companies (Share Capital and Debentures) Rules, 2014 requires a minimum of one year between grant and vesting for unlisted companies.
- RSUs and cash-settled SARs break the pattern. SARs are remeasured at every reporting date, and for RSUs the vesting and delivery dates usually collapse into one taxable moment.
What Actually Changes at Each ESOP Stage?
What changes at each stage is the object being valued and the law that governs it. The grant date belongs to accounting. The exercise date belongs to tax. Vesting belongs to neither, which is precisely why it confuses people.
| Stage | What is valued | Governing framework | Who signs |
| Grant date | The option itself | Ind AS 102, or the ICAI Guidance Note (2020) for non-Ind AS companies | IBBI Registered Valuer |
| Vesting date | Nothing, for equity-settled options | Rule 12(6)(a) sets the timing only | No report required |
| Exercise date | The underlying share | Section 17 of the Income-tax Act, 2025 with Rule 15 of the Income-tax Rules, 2026 | Category I SEBI merchant banker |
Read the last column twice. The professional who signs your grant date report is not permitted to sign your exercise date report, and the reverse is also true. That split is statutory, not a matter of firm preference.
What Happens at the Grant Date?
At grant the company fixes two numbers that behave differently. The exercise price, which the company chooses. The option’s fair value, which a valuer computes.
Does the Companies Act require a registered valuer to set your exercise price?
No. Rule 12(3) of the Companies (Share Capital and Debentures) Rules, 2014 gives an unlisted company the freedom to determine the exercise price, in conformity with its applicable accounting policies. There is no statutory floor tied to a registered valuer’s report.
A widespread misreading creeps in here. Section 62(1)(c), which deals with preferential issues to any persons, does refer to pricing based on a registered valuer’s report. ESOPs are issued under Section 62(1)(b), a different clause with different conditions. Lifting the clause (c) wording across to every ESOP grant is a mistake repeated in many scheme documents.
The board still has to defend the price it picked. Freedom to set the exercise price is not freedom from scrutiny by auditors, investors or an acquirer’s diligence team.
What does Ind AS 102 fix permanently on the grant date?
For an equity-settled award, Ind AS 102 measures the fair value of the option at the grant date and never remeasures it. If the share price triples two years later, the accounting charge does not move by a rupee.
That fair value comes from an option-pricing model fed by the underlying share value, exercise price, expected life, volatility, risk-free rate and dividend yield. Our guide on choosing the option-pricing model that fits the award covers when Black-Scholes-Merton is enough and when a binomial or simulation model is not.
That number then drives the compensation expense across the vesting period. We have set out how the grant-date fair value flows through your P&L over the vesting period separately, including the tranche-by-tranche treatment graded vesting demands.
Companies outside the Ind AS roadmap are not exempt. They apply the ICAI Guidance Note on Accounting for Share-based Payments (2020), which still requires the cost to be recorded.
What does not happen at grant
No tax arises at grant. The employee has received a right to buy shares later, not the shares themselves, and nothing enters payroll. The company files Form MGT-14 within 30 days of the special resolution approving the scheme and records the grant in the Register of Employee Stock Options in Form SH-6.
What Happens at Vesting?
Vesting is the stage almost every ESOP article skips, and it is the stage founders ask about most. The short answer: for a plain equity-settled option, vesting changes the employee’s rights and changes nothing about the valuation.
Is a fresh ESOP valuation required at the vesting date?
No. Vesting is not a taxable event under the Income-tax Act, so no tax FMV is needed. It is not a measurement date under Ind AS 102 either, because the grant-date fair value of an equity-settled award is not remeasured. There is also no filing requirement at vesting under the Companies Act.
Vesting means only one thing legally. The option has become exercisable. The employee can now choose to buy the shares, or wait, or let the options lapse.
Why does the expense change at vesting if the valuation does not?
Because the company revisits the quantity, not the price. Ind AS 102 requires the company to update its estimate of how many options are expected to vest, based on actual attrition and on whether service and non-market performance conditions have been met.
That is an estimate revision, not a revaluation. The fair value per option stays where the grant-date report put it. Only the number it is multiplied by moves. Teams that call this “our vesting valuation” are describing a true-up, and auditors read the phrase the way the standard defines it.
The work at vesting is administrative. Update the SH-6 register, refresh the forfeiture estimate from your own attrition data, and confirm the scheme’s vesting conditions were actually met before options are released.
How long must the gap between grant and vesting be?
Rule 12(6)(a) of the Companies (Share Capital and Debentures) Rules, 2014 requires a minimum of one year between grant and vesting. The only carve-out is where options replace options held in a merged or amalgamated company, where the earlier holding period counts.
The familiar four-year schedule with a one-year cliff is a design convention, not a statutory requirement. The law prescribes only the one-year minimum.
When is vesting a measurement or tax date?
| Instrument | Is vesting a measurement date? | Is vesting a tax date? |
| Equity-settled ESOP | No. Fair value fixed at grant | No. Tax arises at exercise |
| RSU | No. Fair value fixed at grant | Usually yes, because vesting and delivery normally coincide |
| Cash-settled SAR or phantom stock | Yes. Remeasured at every reporting date until settlement | On cash settlement |
Three instruments behave differently, and mixing them up produces real errors in both the P&L and the payroll run.
A company that grants SARs to avoid dilution and budgets for a single grant-date valuation has mispriced the engagement. Cash-settled awards need a fresh fair value at every balance sheet date, and every movement runs through profit or loss.
What Happens at the Exercise Date?
Exercise is where the money moves and the compliance risk concentrates. The employee pays the exercise price, the company allots shares, and a taxable perquisite crystallises.
Who is allowed to sign the exercise date FMV?
Under Section 17 of the Income-tax Act, 2025, specified securities allotted or transferred by an employer free of cost or at a concessional rate are taxed as a perquisite. The value is the fair market value of the share on the exercise date, reduced by what the employee actually paid.
Rule 15 of the Income-tax Rules, 2026 prescribes how that FMV is arrived at. Listed shares use exchange-price mechanics. For an unlisted equity share, the FMV must be determined by a Category I merchant banker registered with SEBI.
An IBBI Registered Valuer cannot substitute for that certificate, and neither can a chartered accountant’s valuation. It is the mirror image of the grant stage, where the accounting fair value is the registered valuer’s territory. Our page on valuation under the Income Tax Act sets out which report each tax provision calls for.
How does the 180-day specified date work?
The specified date is the date the option is exercised, or an earlier date falling not more than 180 days before it. That window is what makes exercise windows practical to administer.
It is also a hard planning constraint. A certificate dated in April cannot support an exercise the following January, because the gap exceeds 180 days. Commission the certificate to sit inside the exercise window, not ahead of the financial year for convenience.
A stale certificate is not a paperwork slip. It exposes the employer to a TDS default and the employee to additional tax and interest, especially where a funding round in the interim points to a higher value.
What else the exercise date triggers
The employer deducts TDS on the perquisite under Section 392 of the Income-tax Act, 2025, the successor to Section 192. The company files Form PAS-3 for the return of allotment and issues share certificates.
Employees of eligible startups may defer the tax. Under Section 392(3) read with Section 289(3), payment runs to the earliest of 60 months from the end of the relevant tax year, the sale of the shares, or cessation of employment. That 60-month window replaced the old 48-month one, so pre-April-2026 scheme documents carry a stale figure. Eligibility is narrow: DPIIT recognition plus a certificate under Section 140, the successor to Section 80-IAC.
On a later sale, Section 73 treats the FMV already taxed as the cost of acquisition. The capital gain runs from the exercise date FMV, not the exercise price paid.
A worked example across all three stages
Take a Bengaluru-based logistics software company. On 1 May 2026 it grants 20,000 options at an exercise price of INR 80. A valuer computes a grant-date fair value of INR 46 per option. Vesting is 25 percent a year over four years, with a 12 percent forfeiture estimate supported by three years of attrition data.
- At grant: options expected to vest are 17,600. Total accounting charge is 17,600 multiplied by INR 46, or INR 8,09,600, recognised across the vesting period tranche by tranche.
- At the first vesting date, 1 May 2027: 5,000 options vest. No valuation is commissioned, no tax is deducted, no form is filed. The company updates the SH-6 register and revisits the forfeiture estimate.
- At exercise on 10 August 2029: the employee exercises 5,000 vested options. The merchant banker FMV on the specified date is INR 310. The perquisite is 5,000 multiplied by INR 230, or INR 11,50,000, added to salary with TDS deducted at exercise.
Notice what the numbers do not do. The INR 46 never appears in the tax computation. The INR 310 never changes the accounting charge. Both are correct about different things. Figures are illustrative and exclude slab rate, surcharge and cess.
Do you have a report for each stage, or one report doing two jobs?
MyValuation issues the grant-date option fair value certified by an IBBI Registered Valuer, and the exercise-date share FMV certified through SEBI-registered Category I merchant bankers. Each report carries the model workings, input support and sensitivity tables your auditor and assessing officer will ask for. Reports are issued in 5 to 7 business days.
Explore our ESOP valuation servicesWhat Do Founders Get Wrong About the Three Stages?
Seven errors account for most of the ESOP adjustments and notices we see. Every one is a stage confusion.
- Reusing the grant-date option value as the exercise-date share FMV. An option value and a share value are different economic objects. The tax rule asks for the share.
- Commissioning a valuation at vesting because it feels like a milestone. For equity-settled options it buys nothing statutory. Spend the fee on the exercise-window certificate instead.
- Letting the merchant banker certificate age past 180 days. The certificate must sit inside the specified-date window that ends on the exercise date.
- Asking the wrong professional to sign. Registered valuer at grant, Category I merchant banker at exercise. Neither is a substitute for the other.
- Treating a funding round price as the ESOP number. Preference rights, liquidation preferences and conversion terms mean the round price is rarely the value of an ordinary share.
- Citing 1961 Act sections in schemes and grant letters signed after 1 April 2026. Section 192 is now Section 392, Form 16 is now Form 130, and the startup deferral is 60 months, not 48.
- Assuming cash-settled SARs need one valuation. They need one at grant and one at every reporting date until settlement.
The renumbering ran wider than the sections. Valuation rules moved too, as we traced in Rule 11UA renumbered as Rule 57. For every framework that touches an ESOP, see the full 2026 ESOP compliance framework.
Worried a grant letter or scheme document is citing law that no longer exists?
We review ESOP schemes, grant letters and board resolutions against the Income-tax Act, 2025, the Income-tax Rules, 2026 and the current Companies Act position, then tell you exactly which clauses need amending before your next grant or exercise window opens.
See how FMV is built for an unlisted company’s sharesConclusion: Getting Your ESOP Grant Date Valuation and Exercise Date FMV Right
An ESOP grant date valuation in India measures the option under Ind AS 102 and is fixed permanently at grant. The exercise date valuation measures the share under Rule 15 of the Income-tax Rules, 2026 and drives the employee’s perquisite tax. Vesting sits between them and requires neither for a standard equity-settled option. Once you hold those three facts, the rest of ESOP compliance becomes scheduling rather than guesswork.
Five things to act on before your next grant or exercise window:
- Map each ESOP event to its stage before commissioning any report, so you buy the valuation the event actually needs.
- Book the merchant banker certificate inside the 180-day window that ends on the exercise date, not at a convenient point in the financial year.
- Check the signatory on every report. Registered valuer at grant, Category I merchant banker at exercise.
- Update scheme documents and grant letters that still cite 1961 Act sections, Form 16 or a 48-month deferral.
- Separate your SAR and phantom stock plans in the valuation budget, because they need a fresh fair value at every reporting date.
Get those five right and your ESOP file stops being an annual argument with your auditor.
Ready to line up the right valuation for your next grant or exercise window?
Tell us the event, the date and the instrument, and we will confirm which report you need, which professional must sign it and what documents to send. Grant-date and exercise-date reports are both delivered in 5 to 7 business days, with priority handling for exercise windows and audit deadlines.
Speak to our valuation teamFrequently Asked Questions
1. Is ESOP taxed at vesting or at exercise in India?
ESOPs are taxed at exercise, not at vesting. Vesting only makes the option exercisable and creates no tax liability. The perquisite arises when the employee exercises and receives shares.
2. Do we need a valuation report on the vesting date?
Not for a standard equity-settled option. Vesting is neither a measurement date under Ind AS 102 nor a taxable event under the Income-tax Act. Cash-settled SARs are the exception, as they are remeasured at every reporting date.
3. Can the grant-date valuation be used for exercise-date tax?
No. The grant-date report values the option for accounting. The tax rule requires the fair market value of the share on the exercise date, determined for unlisted companies by a Category I SEBI merchant banker.
4. How long is a merchant banker FMV certificate valid for an ESOP exercise?
The specified date is the exercise date or an earlier date not more than 180 days before it. A certificate older than that window cannot support the perquisite computation for that exercise.
5. Does the Companies Act require a registered valuer to fix the exercise price?
Rule 12(3) of the Companies (Share Capital and Debentures) Rules, 2014 gives unlisted companies freedom to determine the exercise price in conformity with applicable accounting policies. The registered-valuer pricing wording sits in Section 62(1)(c), which governs a different issuance route.
6. Who signs the grant-date valuation and who signs the exercise-date FMV?
The grant-date option fair value for accounting is issued by an IBBI Registered Valuer. The exercise-date share FMV for unlisted companies must be determined by a Category I merchant banker registered with SEBI under Rule 15.
7. What changed for ESOPs under the Income-tax Act, 2025?
The framework is largely the same but the numbering is not. Section 17 carries the perquisite provision, Rule 15 of the Income-tax Rules, 2026 prescribes FMV, TDS moves to Section 392, and the eligible-startup deferral window runs 60 months instead of 48.
8. Do RSUs and SARs follow the same three stages?
Not exactly. RSU vesting and share delivery usually happen on the same date, so the taxable moment lands at vesting. Cash-settled SARs create a liability that is remeasured at every reporting date and settled in cash rather than shares.