 Parth Shah
on
Parth Shah
Registered Valuer | CA | CPA | 15+ Years of Experience
Parth Shah is the Founder and Team Leader of the company, bringing extensive expertise in business valuation and financial advisory.
Most startup employees can tell you how many ESOPs they hold. Far fewer can tell you what those options are worth, what happens to them when the company raises money, or how much tax they will owe on the day they buy the shares. That gap is why HR and finance teams need a simple way to explain how ESOP works for employees in India.
The gap is well documented. A survey of more than 50,000 employees across 150+ Indian startups, run by scaling platform xto10x and reported by People Matters, found that the startups employees rated lowest commonly had poor ESOP planning and weak communication about rewards. An ESOP that nobody understands does not retain anyone.
This guide gives founders, HR heads and finance teams plain-English language for the three topics employees ask about most: valuation, dilution and tax. MyValuation prepares the reports behind ESOP grants and exercises through its ESOP valuation services, and the questions below are the ones those numbers most often raise.
Key Takeaways
- How ESOP works for employees in India: the employee gets a right to buy a fixed number of shares at a fixed price after a vesting period of at least one year, and pays tax when they exercise and again when they sell.
- The funding round price investors pay is usually higher than the value of an employee’s ordinary share, because investor shares carry extra rights.
- Dilution lowers the percentage an employee owns, never the number of options they hold.
- At exercise, the share’s fair market value minus the exercise price is a perquisite, taxed as salary, with TDS under Section 392 of the Income-tax Act, 2025.
- For an unlisted company, that fair market value comes from a SEBI Category I merchant banker, dated no more than 180 days before exercise.
- Employees of eligible start-ups can defer the perquisite tax for up to 60 months after the tax year ends, or until they sell or leave, if earlier.
- Unlisted ESOP shares sold more than 24 months after exercise are taxed at 12.5% long-term capital gains on the growth after exercise.
How Does an ESOP Work for Employees in India?
An ESOP (employee stock option plan) gives an employee the right, but not the obligation, to buy a set number of company shares at a price fixed today. The employee earns that right over time and pays only if they choose to buy.
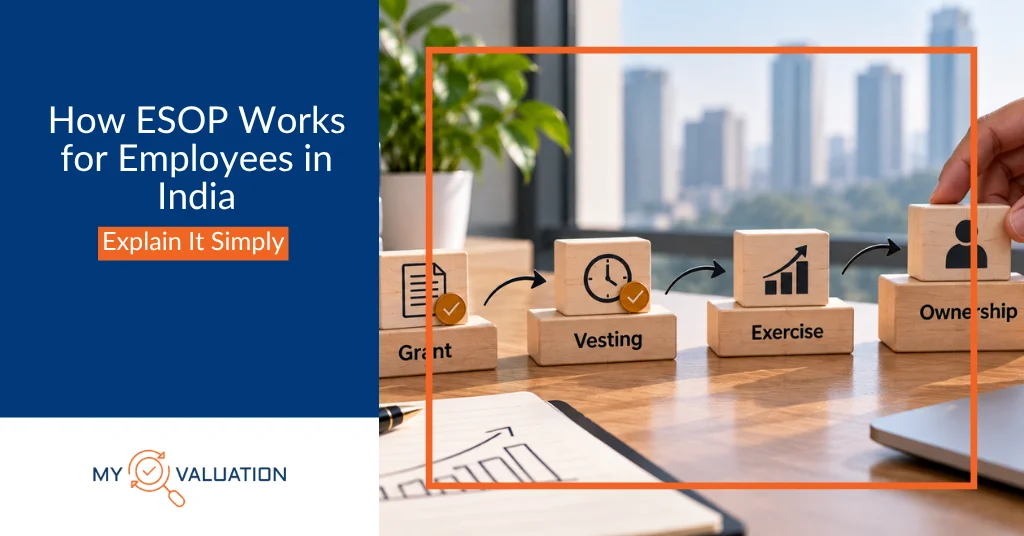
Explain it as four steps that happen on four different dates:
- Grant: the company promises the employee, say, 4,000 options at INR 100 each. Nothing is paid and nothing is taxed.
- Vesting: the employee earns the right to use those options over time, typically in yearly slices. Indian company law requires at least one year between grant and vesting.
- Exercise: the employee pays the exercise price and receives real shares. This is the first tax moment.
- Sale: the employee sells the shares in a buyback, a secondary sale or after a listing. This is the second tax moment.
The key sentence for any town hall is this: an option is not a share until you pay for it. Employees who grasp that one line ask far better questions about everything else.
The ESOP vocabulary in plain English
Jargon is the first barrier. Use this table as the glossary page of your ESOP explainer.
| Term | What it means | What to say to employees |
| Option | A right to buy one share later | “A coupon, not a share” |
| Exercise price | The fixed price you pay per share | “Your locked-in price” |
| Vesting | Earning the right to use options | “Unlocking your coupons over time” |
| Cliff | The wait before the first slice vests | “Nothing unlocks before year one” |
| Fair market value (FMV) | The tax value of one share on a date | “What the tax law says a share is worth” |
| Perquisite | FMV minus exercise price, taxed as salary | “Your on-paper gain at purchase” |
| Dilution | New shares shrink each holder’s percentage | “A bigger pie, a thinner slice” |
| Liquidity event | A chance to sell for cash | “The day paper becomes money” |
Why Do Employees Misunderstand Their ESOPs?
Employees misunderstand ESOPs mainly because companies talk about them in the wrong units. A grant letter shows a number of options, an offer call mentions a percentage, and a founder’s LinkedIn post celebrates a valuation. None of those three numbers is what the employee will actually take home.
Three misreadings come up again and again:
- Headline valuation equals my wealth. An employee multiplies their options by the last round price and treats the result as money already earned.
- A percentage is fixed. They hear “0.4% of the company” and assume it stays 0.4% forever.
- Tax comes only when I sell. They do not realise that buying the shares can trigger a large tax bill with no cash in hand.
Each of these maps to one of the three topics below. Fix them in that order: valuation, dilution, tax.
How Do You Explain What an ESOP Is Actually Worth?
An ESOP is worth the value of the share it lets you buy, minus the price you pay for it, and only once you can sell. The honest answer to “what are my options worth?” always has three parts: the share value, the exercise price and the chance of a sale.
Why the funding round price is not your share price
Investors usually buy preference shares, not the ordinary shares employees receive. Preference shares often carry rights such as getting their money back first in a sale. Those rights make an investor share worth more than an ordinary share.
So when a startup raises money at INR 2,000 per share, an employee’s ordinary share may be valued at INR 1,200 for tax purposes. Both numbers can be correct. Say it plainly: “Investors paid for extra protection. Your share does not have that protection, so it is valued lower.”
The three numbers on an employee’s paperwork
Every employee will eventually see three different numbers attached to their ESOPs. Name them before anyone asks:
- Exercise price: what they pay per share, fixed in the grant letter.
- Exercise-date FMV: the tax value of the share on the day they buy, set by a valuation report.
- Grant-date option fair value: an accounting number the company books as an expense, which never touches the employee’s tax.
The third number confuses people when it appears in annual reports or board decks. For the full technical split between these values, see our guide on what changes at grant, vesting and exercise.
How Do You Explain Dilution Without Scaring People?
Dilution happens when a company issues new shares, so every existing holder owns a smaller percentage of a company that is usually worth more. The employee still holds exactly the same number of options after a funding round.
The pizza analogy works because it is accurate. If a pizza cut into 10 slices becomes a bigger pizza cut into 12 slices, your one slice is a smaller share of the whole. Whether your slice got bigger or smaller depends on how much the pizza grew.
Talk in shares, not percentages
Percentages invite disappointment because they only ever go down. Share counts stay fixed, and the value per share is what moves. Train managers to say “you hold 4,000 options” rather than “you own 0.4%”.
When dilution comes up, show the employee three lines: shares held before the round, shares held after the round (identical), and the value per share before and after. If you need the mechanics for your own team first, our explainer on how pre-money and post-money valuation work covers how a new round changes ownership.
How Is an ESOP Taxed for Employees in India?
An ESOP is taxed twice in India: once when the employee exercises and buys the shares, and again when they sell them. There is no tax at grant or at vesting.
At exercise, Section 17(1)(d) of the Income-tax Act, 2025 treats the share’s fair market value minus the price paid as a perquisite. That amount is added to salary and taxed at the employee’s slab rate. The employer deducts TDS on it under Section 392.
At sale, the FMV already taxed becomes the employee’s cost. Only the growth after exercise is taxed again, as capital gains. For unlisted shares held more than 24 months, long-term gains are taxed at 12.5% under Section 197; shorter holdings are taxed at slab rates.
The cash an employee needs at exercise
This is the point most employees miss. At exercise they pay twice from their own pocket: the exercise price to the company, and the tax on a gain they cannot yet sell. For an unlisted startup, that tax is due on paper wealth with no buyer in sight.
The FMV that drives this tax must come from a SEBI Category I merchant banker under Rule 15 of the Income-tax Rules, 2026, dated on or within 180 days before the exercise date. Our full 2026 ESOP tax and compliance guide sets out the rule in detail.
The startup deferral and when it ends
Employees of an eligible start-up, one certified under Section 140 of the Income-tax Act, 2025, can delay paying the perquisite tax. Under Section 289(3), the tax becomes payable within 14 days after the earliest of three events: 60 months from the end of the relevant tax year, the sale of the shares, or leaving the company.
Many older explainers still say 48 months. That was the rule under the 1961 Act. Make sure your ESOP FAQ and grant letters carry the current figure.
Worked Example: Explaining One Employee’s ESOPs From Grant to Sale
A worked example does more than any policy document. Here is one you can adapt for an anonymised employee at a Pune-based SaaS startup. All figures are illustrative.
| Stage | What happens | Number to share |
| Grant | 4,000 options at INR 100; 10,00,000 shares in total | 0.40% ownership |
| Series B | 2,50,000 new shares issued at INR 2,000 | Still 4,000 options; now 0.32% |
| Exercise | Pays 4,000 x INR 100 | INR 4,00,000 paid |
| Perquisite | FMV INR 1,200 less INR 100, x 4,000 | INR 44,00,000 taxable |
| Tax at exercise | Assumed 30% slab plus 4% cess | INR 13,72,800 |
| Sale after 3 years | Sold at INR 2,000; gain over INR 1,200 | INR 32,00,000 gain |
| Tax on sale | 12.5% long-term capital gains | INR 4,00,000 |
Valuation: the investors paid INR 2,000, but the employee’s ordinary share was valued at INR 1,200 for tax. The difference reflects the investors’ preference rights, not a mistake.
Dilution: ownership fell from 0.40% to 0.32%, yet the share value rose from the INR 100 exercise price to INR 1,200. The employee is clearly better off despite the smaller percentage.
Tax: to exercise, the employee needs about INR 17.7 lakh in cash (INR 4 lakh price plus INR 13.7 lakh tax) before selling a single share. If the startup is eligible for deferral, the INR 13.7 lakh can wait until the earliest of the 60-month point, the sale, or leaving the company.
The figures exclude surcharge and assume the sale is to a secondary buyer. A company buyback is taxed differently, so check the route before any liquidity event.
Can your exercise-date FMV stand up to an employee’s questions?
MyValuation coordinates exercise-date FMV reports through SEBI-registered Category I merchant bankers, dated to fit your exercise window. Each report explains why the ordinary share value differs from the last round price, so HR has a clear answer ready. Reports are delivered in 5 to 7 business days.
Get an exercise-date FMV for your next windowWhat Should an ESOP Explainer Pack for Employees Include?
A good ESOP explainer pack lets an employee answer their own questions without booking a call with finance. Build it once and update it after every funding round or exercise window.
- A one-page summary of the four steps (grant, vest, exercise, sell) in plain English.
- A personalised statement showing options granted, vested, exercise price and the latest FMV.
- A tax illustration using the employee’s own numbers, with the cash needed at exercise shown clearly.
- The glossary table from this guide, adapted to your scheme’s wording.
- A dilution note after each round, showing share count unchanged and value per share before and after.
- Leaver rules: what happens to vested and unvested options on resignation, and how long the exercise window stays open.
- A live session with HR and finance, recorded for new joiners.
Keep the cap table behind the pack accurate. Our list of common cap table mistakes founders make shows where share counts usually go wrong.
Common Mistakes When Explaining ESOPs to Employees
The most damaging ESOP communication mistakes are the ones that set expectations too high. Each one turns into a difficult conversation later.
- Selling paper value as wealth. Multiplying options by the latest round price overstates what an ordinary share is worth.
- Quoting percentages. A promised percentage will shrink with every round and read as a broken promise.
- Using the round price as the tax value. The tax FMV for unlisted shares must come from a merchant banker’s report, not from a term sheet.
- Hiding the cash needed at exercise. Employees who discover the tax bill late often let options lapse.
- Citing the old 48-month deferral. The current window for eligible start-ups is 60 months.
- Implying a guaranteed exit. Say clearly that there is no fixed date for a buyback or listing.
- Letting the valuation go stale. An FMV dated more than 180 days before exercise cannot support the tax calculation, a point covered on our page on valuation under the Income Tax Act.
Is the number in your grant letter one you can defend?
We review ESOP schemes, grant letters and employee FAQs against the Income-tax Act, 2025 and the Income-tax Rules, 2026, then flag the figures and section references that need updating. You get a short written note before your next grant cycle or exercise window opens.
Book a review of your ESOP documentsConclusion: Explaining How ESOP Works for Employees in India
Explaining how ESOP works for employees in India comes down to three plain truths. An option is a right to buy at a fixed price, worth something only once there is a sale. Dilution shrinks the percentage but never the number of options. Tax arrives twice, and the first bill lands at exercise, before any cash comes in.
Four actions will close most of the literacy gap in your team:
- Replace percentages with share counts in every offer call, grant letter and statement.
- Show the cash needed at exercise using each employee’s own numbers, before their first window opens.
- Explain why the round price and the tax FMV differ every time a new round closes.
- Update every ESOP document to the 2025 Act references and the 60-month deferral.
Do that, and ESOPs start doing the job they were granted for: keeping good people.
Planning an exercise window or a new grant cycle?
Tell us the event, the date and the number of employees involved. We will confirm which valuation report you need, who must sign it and how to present the result to your team. Grant-date and exercise-date reports are delivered in 5 to 7 business days.
Speak to our ESOP valuation teamFrequently Asked Questions
1. Is ESOP taxed at vesting in India?
No. Vesting only gives the employee the right to exercise. Tax arises when the employee exercises and buys the shares, and again when they sell them.
2. Does dilution reduce the value of my ESOPs?
Dilution reduces your percentage, not your number of options. Your value per share can still rise if the new round values the company higher than before.
3. Why is my share’s FMV lower than the funding round price?
Investors usually buy preference shares with extra rights, such as being paid first on a sale. Employees hold ordinary shares without those rights, so their value is typically lower.
4. Do I pay tax if I exercise but do not sell?
Yes. The FMV minus the exercise price is taxed as salary in the year you exercise, even if you have not sold. Eligible start-up employees can defer payment.
5. What happens to my ESOPs if I leave the company?
Unvested options usually lapse when you leave. Vested options can generally be exercised within a window set by your company’s scheme, so check the leaver clause.
6. Who decides the FMV of an unlisted company’s shares for ESOP tax?
A SEBI-registered Category I merchant banker, under Rule 15 of the Income-tax Rules, 2026. The valuation date must fall on or within 180 days before the exercise date.
7. How long can a startup employee defer ESOP tax?
Up to 60 months from the end of the relevant tax year for eligible start-ups. Tax becomes due earlier if the employee sells the shares or leaves the company.