 Parth Shah
on
Parth Shah
Registered Valuer | CA | CPA | 15+ Years of Experience
Parth Shah is the Founder and Team Leader of the company, bringing extensive expertise in business valuation and financial advisory.
ESOP Vesting Schedule Design: How to Structure Cliff and Graded Vesting for Indian Startups
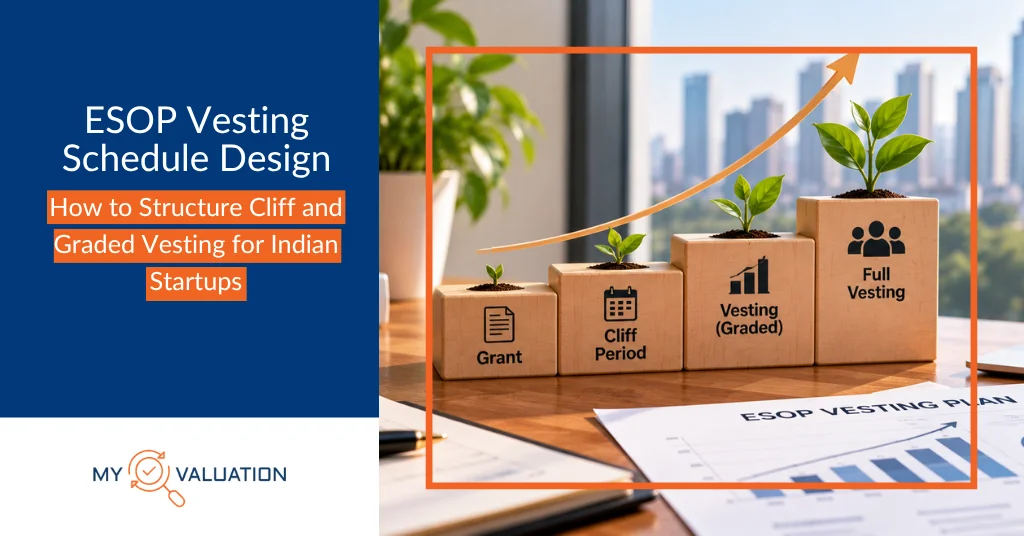
The most common ESOP vesting schedule in India is four years with a one-year cliff. Nothing vests in year one, 25% vests on the first anniversary, and the rest vests monthly or quarterly over the next three years.
That default is a market habit, not a legal rule. Indian company law only asks for a minimum one-year gap between grant and vesting. Everything else, including the cliff, the pace and the leaver terms, is a design choice you make for your company.
Those choices matter more now. Startups are competing hard for the same engineers, product leads and sales heads, and a well-built vesting schedule is one of the few retention tools that costs no cash. At MyValuation, we see the same pattern across ESOP mandates: the schedule decides how well the plan retains people long before the valuation number does.
This guide explains what the law requires, how cliff vesting and graded vesting compare, and how to design a schedule step by step.
Key Takeaways
- An ESOP vesting schedule in India most often runs four years with a one-year cliff, but only the one-year minimum between grant and vesting is mandatory.
- Unlisted companies follow Rule 12(6)(a) of the Companies (Share Capital and Debentures) Rules, 2014. Listed companies follow Regulation 18 of the SEBI SBEB & SE Regulations, 2021.
- On death or permanent incapacity, the law overrides the schedule: options granted up to that date vest, and pass to legal heirs on death.
- On resignation or termination, unvested options lapse, while vested options can be exercised within the period your scheme specifies.
- Cliff vesting releases a block of options on one date. Graded vesting releases them in instalments over time. Most startups combine both.
- Under Ind AS 102, each graded tranche is expensed as a separate award, so graded vesting puts more ESOP cost into the early years.
- Vesting is not a tax event. The employee is taxed when shares are allotted on exercise, not when options vest.
What Is an ESOP Vesting Schedule?
An ESOP vesting schedule is the timetable that decides when an employee earns the right to buy the options they were granted. Until options vest, the employee holds a promise, not a right.
Three dates sit at the centre of every ESOP:
- Grant date: the company awards the options and fixes the exercise price.
- Vesting date: the employee earns the right to exercise some or all of those options.
- Exercise date: the employee pays the exercise price and receives shares.
The vesting schedule controls the gap between the first two dates. It is written into the ESOP scheme and the individual grant letter. We cover what changes in valuation terms at each date in our guide to ESOP valuation at grant, vesting and exercise.
What Does Indian Law Require for ESOP Vesting?
Indian law sets a floor and a few protections. It does not prescribe a cliff, a four-year term or a vesting frequency.
Unlisted companies: Rule 12 of the Share Capital Rules
For unlisted companies, Rule 12(6)(a) of the Companies (Share Capital and Debentures) Rules, 2014 says there must be a minimum period of one year between grant and vesting. No option can vest earlier, even partly.
Rule 12(8) adds the protections that override your schedule:
- Options cannot be transferred, pledged or mortgaged.
- On death in service, all options granted up to that date vest in the legal heirs or nominees.
- On permanent incapacity in service, all options granted up to that date vest on that day.
- On resignation or termination, unvested options expire. Vested options can still be exercised within the period the scheme specifies.
Employees also get no dividend or voting rights on options until shares are actually issued.
Listed companies: SEBI SBEB & SE Regulations
Listed companies follow Regulation 18 of the SEBI (Share Based Employee Benefits and Sweat Equity) Regulations, 2021. It also sets a minimum one-year vesting period, waived on death or permanent incapacity. The company must frame a written policy for those two cases.
Cliff Vesting vs Graded Vesting: What Is the Difference?
Cliff vesting means a block of options vests all at once on a single date, with nothing vesting before it. Graded vesting means options vest in instalments, such as 25% a year or a fixed slice every quarter.
The two are not rivals. The classic startup schedule uses a cliff first and graded vesting after it. The real design question is how long the cliff should be and how the rest should flow.
| Feature | Cliff vesting | Graded vesting |
| How options vest | One block on one date | Instalments over time |
| Retention pull | Strong until the cliff, then drops | Steady through the term |
| Early leaver outcome | Leaves with nothing | Keeps vested instalments |
| Admin effort | Low | Higher, more vesting events |
| Ind AS 102 expense | Spread evenly to cliff date | Front-loaded, tranche by tranche |
| Best suited for | Probation-style protection | Long-term retention |
What Vesting Structures Do Indian Startups Commonly Use?
Most Indian startup schemes use one of four structures. Each suits a different stage and hiring need.
Four years with a one-year cliff
This is the default. 25% vests at the end of year one, then the remaining 75% vests monthly or quarterly over 36 months. It satisfies the one-year legal minimum and is easy for employees to understand.
Equal annual vesting
Here 25% vests on each anniversary for four years. It is simpler to administer than monthly vesting, but employees who leave mid-year lose up to eleven months of progress, which can feel harsh.
Back-loaded vesting
A back-loaded schedule vests smaller amounts early and larger amounts later, for example 10%, 20%, 30% and 40% over four years. It rewards people who stay longest. It also tells candidates the company expects a long journey, so explain it clearly at offer stage.
Performance-linked vesting
Some options vest only when a target is met, such as a revenue milestone, a product launch or a funding round. This works well for senior leaders. The targets must be measurable and written down, or disputes follow.
Many companies blend these. A common hybrid is time-based vesting for most of the grant, with a smaller performance-linked slice for leadership roles.
How Do You Design an ESOP Vesting Schedule Step by Step?
A good schedule starts from the business plan, not from a template. Work through these six steps before the Board approves the scheme.
- Set the retention horizon. Ask how long you need key people to stay. If your exit or next major milestone is five years away, a three-year schedule leaves a gap.
- Choose the cliff length. One year is standard and matches the legal minimum. A longer cliff protects the company but makes offers less attractive.
- Pick the vesting frequency after the cliff. Monthly vesting feels fairest to employees. Quarterly or annual vesting means fewer vesting events to track and record.
- Decide the role mix. Use time-based vesting for most staff and consider a performance slice for leadership. Keep the structure consistent within each band.
- Write clear leaver terms. Define good and bad leavers, the post-exit exercise window and what happens to vested options in each case.
- Plan for a sale. Decide whether any vesting accelerates on an acquisition, and under what conditions.
Once the schedule is set, check how it changes ownership as options vest and convert. Our post on cap table mistakes founders make shows how unplanned ESOP dilution creates problems at the next round.
Not sure which vesting schedule fits your hiring plan and runway?
MyValuation reviews your draft ESOP scheme, tests the vesting schedule against your retention goals and exit timeline, and flags legal gaps before Board approval. You get a written review note with specific changes, usually within a week.
Book a vesting schedule reviewHow Does the Vesting Schedule Affect ESOP Expense and Valuation?
The vesting schedule directly changes the ESOP expense in your profit and loss account. Founders often miss this when they choose a structure.
Under Ind AS 102, a graded schedule is treated as several separate awards, one per tranche, each with its own vesting period. The year-one tranche is expensed fully in year one, while the year-four tranche is spread over four years. The result is a heavier charge in the early years. We walk through the numbers in our guide to calculating ESOP expense tranche by tranche.
Performance conditions also affect the valuation model. A market-based condition, such as a share price target, usually needs a simulation approach rather than a simple formula. Our comparison of Black-Scholes, Binomial and Monte Carlo models explains when each fits.
On tax, vesting itself does not trigger anything. The employee is taxed on the perquisite when shares are allotted on exercise, based on the fair market value at that time. Our complete ESOP valuation and taxation guide covers those rules.
What Happens to Vesting When an Employee Leaves or the Company Is Sold?
Leaver and exit terms decide whether your ESOP holds up in real life. They deserve as much attention as the schedule itself.
Good leavers and bad leavers
A good leaver exits for reasons the company accepts, such as retirement or a mutual parting. A bad leaver exits for misconduct or a breach of terms. Many schemes let good leavers keep vested options with a reasonable exercise window, while bad leavers forfeit them.
The law already says unvested options lapse on resignation or termination. Your scheme decides what happens to vested ones and how long the exercise window lasts.
Single-trigger and double-trigger acceleration
Acceleration means unvested options vest early when a defined event happens. With single-trigger acceleration, the sale of the company alone causes vesting. With double-trigger acceleration, vesting happens only if the company is sold and the employee loses their role soon after.
Buyers usually prefer double-trigger terms, because they want the team to stay after the deal. Single-trigger terms can reduce what an acquirer is willing to pay. Remember that any acceleration still cannot breach the one-year minimum from grant.
What Are the Most Common Vesting Design Mistakes?
These are the issues we see most often when reviewing Indian ESOP schemes.
- Vesting before 12 months. Any tranche that vests inside one year of grant breaches Rule 12(6)(a), even for senior hires.
- Copying a US template. US plans often assume rules that do not apply in India, and miss the Rule 12(8) death and incapacity provisions.
- Vague performance targets. “Strong growth” is not a vesting condition. Use a number, a date and a measurement method.
- No exercise window for leavers. Silence in the scheme creates disputes the day a vested employee resigns.
- Ignoring the P&L effect. A graded schedule front-loads expense, which can surprise the finance team and auditors.
- Different terms for similar roles. Inconsistent schedules inside a band breed resentment and are hard to defend.
- Changing the schedule without approval. Varying terms after grant needs the right approvals and must not hurt the employee’s interests.
Would your ESOP scheme survive an auditor’s first read?
Our ESOP team checks the scheme document, grant letters and vesting terms against the Companies Act and Ind AS 102, then delivers the grant-date fair value your auditor needs. Reports are signed by an IBBI Registered Valuer.
Explore ESOP valuation servicesConclusion: Designing an ESOP Vesting Schedule in India That Retains Talent
A strong ESOP vesting schedule in India starts from the one-year legal minimum and builds the rest around your retention horizon. A one-year cliff with graded vesting after it works for most startups, as long as leaver terms, acceleration and expense impact are thought through before grant.
- Match the vesting term to your next major milestone or likely exit, not to a template.
- Keep every tranche outside the first 12 months from grant, including for senior hires.
- Write leaver and exercise-window terms before the first person resigns.
- Model the Ind AS 102 expense for your chosen structure before the Board signs off.
Get those four right and your ESOP becomes a reason to stay, not a source of disputes.
Ready to build an ESOP plan your team understands and your auditor accepts?
MyValuation helps founders design the vesting schedule, review the scheme document and value the options at grant, all under one IBBI Registered Valuer. Share your draft scheme or cap table and we will come back with a clear plan and fee quote.
Get a free ESOP consultationFrequently Asked Questions
1. Is a one-year cliff mandatory for ESOPs in India?
No. The law requires a minimum one-year gap between grant and vesting, but not a cliff as such. In practice, a one-year cliff is the simplest way to meet that minimum, which is why most schemes use it.
2. Can ESOPs vest monthly in India?
Yes, after the first year. Monthly vesting is common once the one-year minimum has passed. No option can vest in the first twelve months from grant.
3. What is the difference between cliff and graded vesting?
Cliff vesting releases a block of options on a single date. Graded vesting releases options in instalments over time. Most Indian startups use a one-year cliff followed by graded vesting.
4. Is ESOP vesting taxable in India?
No. Vesting is not a tax event. The employee is taxed on the perquisite when shares are allotted on exercise, and again on capital gains when those shares are sold.
5. What happens to unvested options when an employee resigns?
Unvested options lapse on resignation or termination under Rule 12(8). Vested options can usually be exercised within the window the ESOP scheme specifies.
6. What happens to ESOPs on an employee’s death?
All options granted up to the date of death vest in the employee’s legal heirs or nominees. The one-year minimum does not apply in this case.
7. Can a company accelerate vesting on an acquisition?
Yes, if the scheme allows it. Acceleration can be single-trigger or double-trigger, but it still cannot cause any option to vest within one year of grant.
8. Can you change a vesting schedule after options are granted?
Yes, with the required approvals, as long as the change does not hurt the interests of employees who already hold options. Document every change in a Board and shareholder resolution.